Australia has quietly become one of the most significant sources of cross-border capital flowing into European luxury real estate. In 2024, Australian buyers accounted for a disproportionate share of international transactions in Spain, Portugal, and Italy - and 2025 shows no sign of slowing this trend. What was once a trickle of lifestyle-motivated purchases has evolved into a sophisticated, yield-conscious wave, driven by a confluence of currency dynamics, residency incentives, and a growing Australian appetite for international asset diversification.
The shift is structural, not cyclical. Domestic property markets in Sydney and Melbourne - perennially among the world's least affordable - have pushed a new generation of high-net-worth Australians toward more accessible luxury markets. Europe, with its deep culture of property ownership, historic inventory, and improving digital infrastructure, has become the natural destination.
The Numbers Behind the Movement
The scale of Australian engagement with European real estate has surprised even seasoned market participants. Cross-border investment flows tracked through 2024 paint a compelling picture of a buyer cohort that is well-capitalised, highly motivated, and increasingly repeat-transacting in European markets.
These figures are not the result of speculative fever. Australian buyers in Europe trend older (median age 48–58), are typically cashing out significant domestic equity, and are purchasing with a dual mandate: lifestyle use combined with capital preservation. Unlike cash-flush buyers from the Gulf or Southeast Asia, Australians tend to purchase for owner-occupancy or premium short-term rental, which has endeared them to local vendors and local authorities alike.
Why Europe, Why Now
Several forces have converged to make 2025 particularly compelling for Australian buyers eyeing European property. The window, while open, will not remain so indefinitely - and those who acted in 2023 and 2024 are already sitting on meaningful gains in both local currency terms and AUD-adjusted values.
A Favourable Exchange Window
The AUD/EUR rate has oscillated between 0.59 and 0.62 over the past 24 months - hardly at historic highs, but significantly stronger than the 2022 trough of 0.64 (inverse). For a €1.5 million Algarve villa, this spread represents a differential of A$80,000–120,000 depending on entry timing. Advisors who assist Australian buyers in European markets consistently cite currency timing as the single most impactful financial lever available to purchasers.
Lifestyle Migration and the Post-COVID Recalibration
The pandemic permanently altered the geography of work for high-earning Australians. Remote and hybrid arrangements have made 90-day European sojourns not merely possible, but professionally unremarkable. Spain and Portugal's investment in English-language infrastructure, international schooling, and digital connectivity has reduced the friction cost of relocation to near-zero for professional families.
Entry Cost Advantage Over Domestic Markets
A €900,000 villa in the Costa Blanca - with a pool, sea views, and 300 square metres of living space - is simply not comparable to what that budget delivers in Sydney's Northern Beaches or Melbourne's Toorak. European luxury property, particularly outside the prime Paris and London markets, offers a structural value advantage that domestic markets cannot replicate. For buyers conditioned to Sydney pricing, the Mediterranean remains a near-permanent bargain.
Residency Pathways
Portugal's Non-Habitual Resident (NHR) tax regime and its reformed Golden Visa programme, alongside Spain's Non-Lucrative Visa (NLV) and newly introduced Startup Visa, have created structured pathways to residency that align neatly with the financial profiles of Australian buyers. The prospect of EU residency - with its associated travel freedoms and tax advantages - has elevated what was once a purely lifestyle decision into a sophisticated wealth management strategy.
The Top Three Markets for Australian Buyers
While Australian capital has touched almost every corner of European luxury real estate, three markets have emerged as the clear centres of gravity - each offering a distinct proposition tailored to different buyer profiles.
Spain - Costa Blanca & Costa del Sol
Spain remains the single largest destination for Australian buyers in Europe, driven by its unmatched combination of climate, infrastructure, and value. The Costa Blanca - stretching from Denia to Torrevieja - offers modern new-build villas at €400,000–€1.8 million, often in purpose-built urbanisations with English-speaking communities and international schools. The Costa del Sol, anchored by Marbella and its Golden Mile, skews higher: €1.5 million to €6 million, with a more established luxury hospitality infrastructure. Australians are particularly drawn to the Costa Blanca's Jávea and Moraira for their relaxed atmosphere and strong Australian expat networks.
Portugal - Lisbon & the Algarve
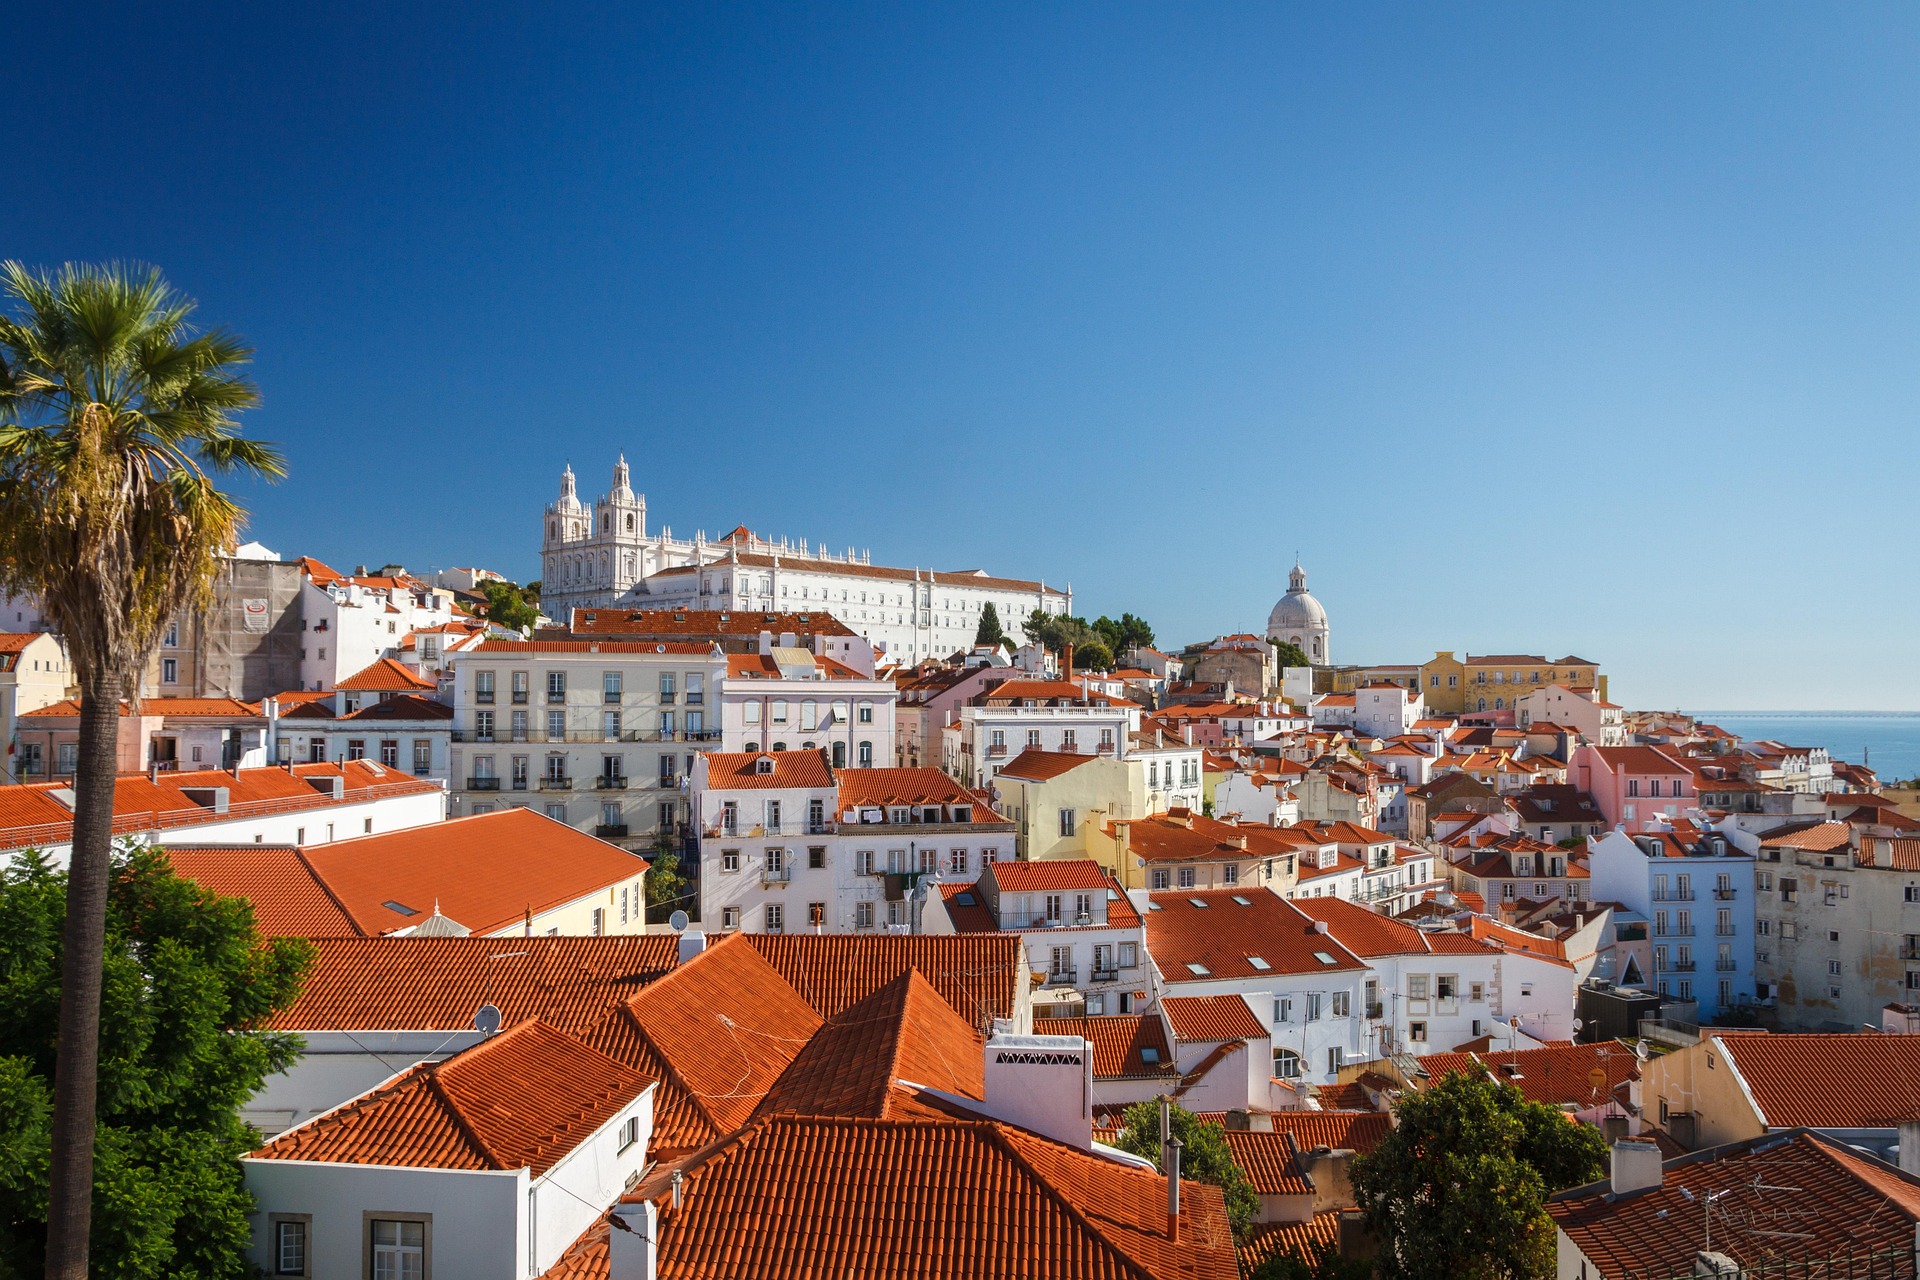
Portugal punches above its weight for Australian buyers due to the NHR tax advantage and a remarkably benign buying process. Lisbon's historic parishes - Príncipe Real, Santos, and Chiado - command €8,000–€15,000 per square metre for renovated palace-style apartments, and have attracted a particularly culturally engaged Australian buyer. The Algarve, meanwhile, offers a more conventionally Mediterranean experience: golf, beaches, and branded resort residences from €600,000 to €3 million. The towns of Carvoeiro and Vilamoura remain the strongest submarkets for Australian purchasers seeking rental yield alongside lifestyle use.
Italy - Tuscany & Lake Como
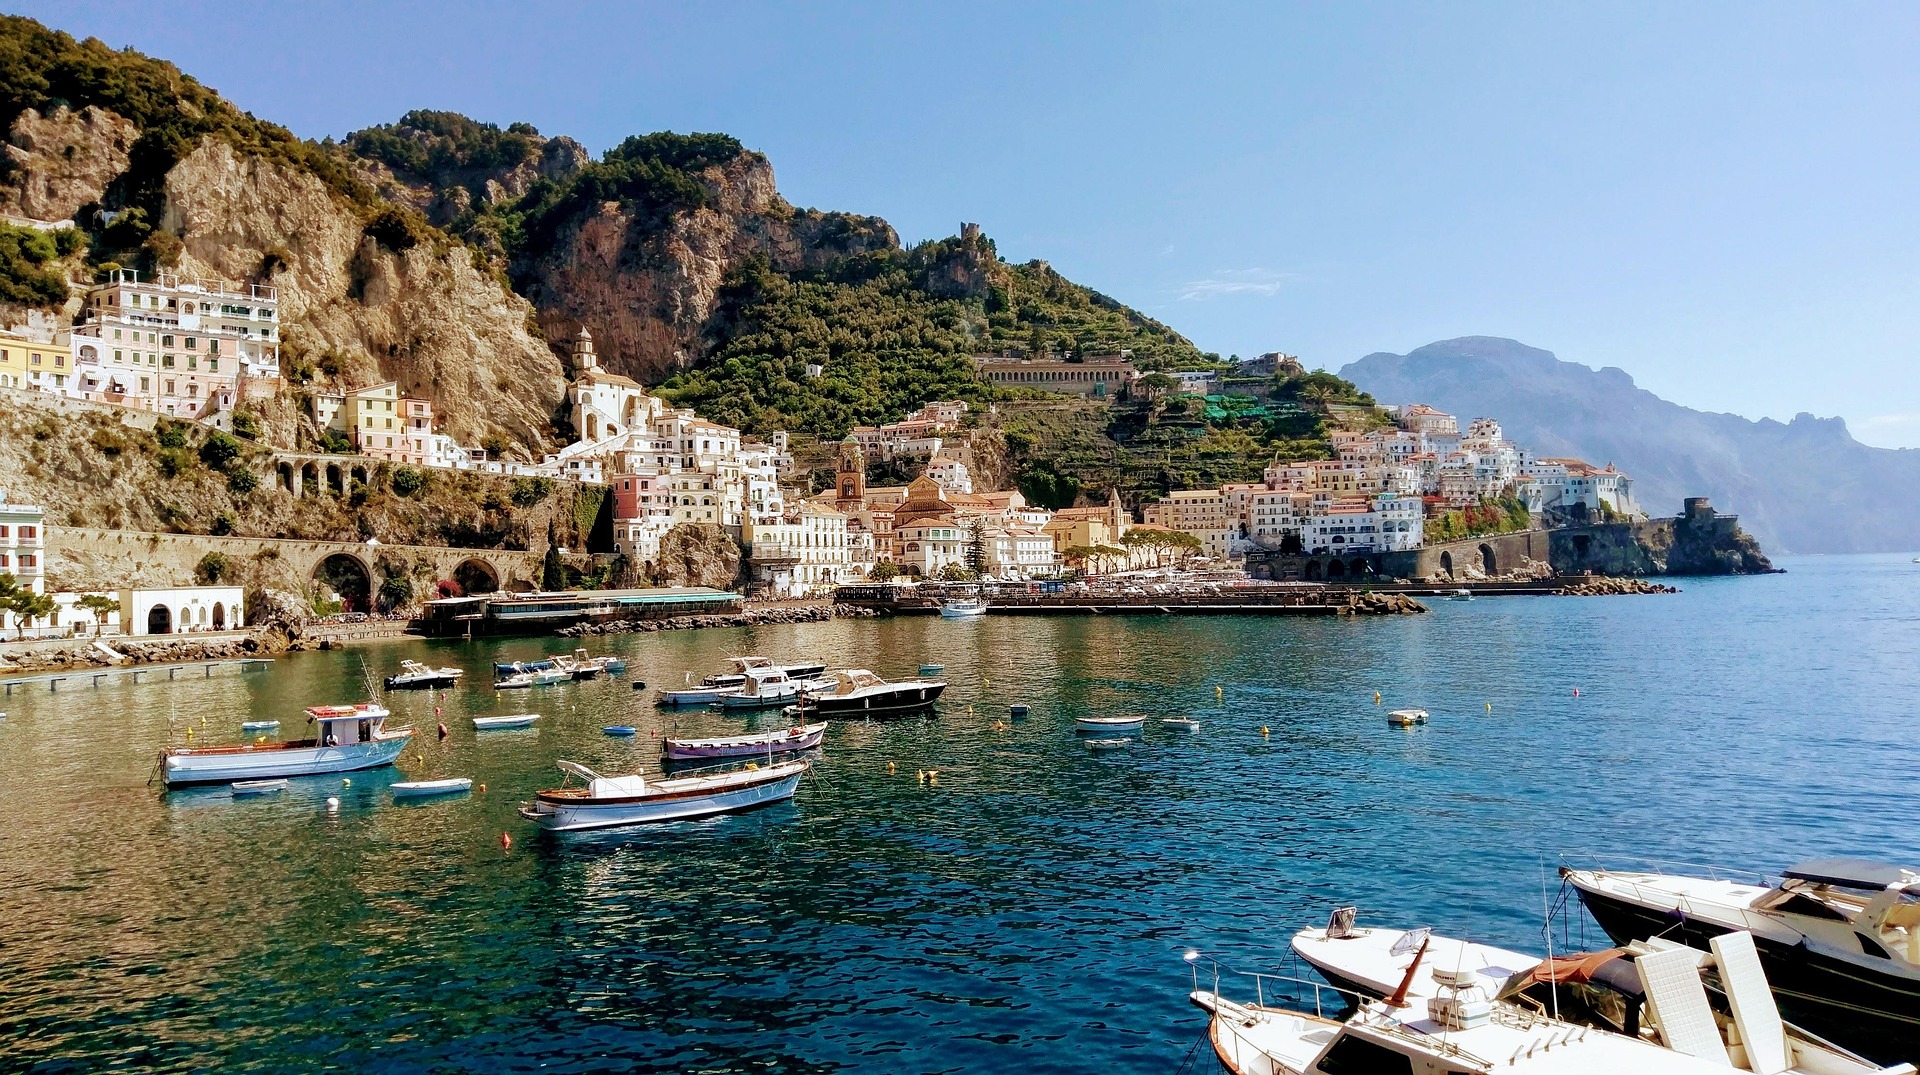
Italy occupies a distinct psychological position in the Australian buyer's imagination - aspirational, cinematic, and culturally magnetic. Tuscany's farmhouse and restored estate market (€500,000–€4 million) attracts buyers for whom authenticity and provenance matter as much as yield. Lake Como, increasingly colonised by ultra-high-net-worth buyers from the Americas and Asia-Pacific, has seen prices rise sharply: waterfront properties now start at €2.5 million and reach €20 million or beyond for the storied villas of Cernobbio and Tremezzo. Italian purchases require particular care around building permits, agricultural land restrictions, and Italian inheritance law - areas where experienced legal counsel is non-negotiable.
The Investment Case: Yield, Appreciation & Income
For buyers who intend to let their European properties - and the majority do - the income potential of Mediterranean markets compares favourably with almost any comparable luxury product in Australian or North American markets.
| Market | Gross Yield | 5-Year Appreciation Forecast | Peak Season Nightly Rate |
|---|---|---|---|
| Spain (Costa del Sol) | 5.5% | +18–22% | €600–€1,400 |
| Portugal (Algarve) | 4.8% | +15–20% | €450–€900 |
| Italy (Tuscany) | 4.0% | +12–16% | €700–€2,200 |
| Italy (Lake Como) | 3.2% | +20–28% | €1,100–€4,500 |
Peak holiday markets - particularly the Costa del Sol, Algarve, and Tuscany - generate the majority of rental income across just 10–14 weeks of summer occupancy. Professional short-term rental management has matured significantly across all three markets, with local operators offering full-service models that deliver hands-off income for international owners. Net yields after management fees typically land between 3.0% and 4.2%, which - against a backdrop of capital appreciation - represents a compelling total return profile.
"The Mediterranean doesn't just offer a home - it offers a hedge. Against currency risk, against overheated domestic markets, and against a pace of life that leaves little room for what matters."
What to Watch in 2025
No market outlook would be complete without an honest assessment of the risks and inflection points that buyers should monitor over the coming twelve months.
Currency Movements
The AUD/EUR relationship remains a function of global risk sentiment, Australian commodity prices, and ECB policy. A sharp AUD depreciation - not an unlikely scenario in a global slowdown - would increase the effective cost of a European purchase by 8–15% with no change in local pricing. Buyers with firm timelines should speak with a currency specialist about forward contract strategies that can lock in current rates for completion.
Election Cycles and Political Risk
Spain's fragmented political landscape has created occasional uncertainty around regional governance in the Balearics and Valencia, where property regulation is most actively contested. Portugal's new government has signalled a broadly pro-investment posture, but the fine print of NHR reform bears close watching. Italy remains politically volatile at the national level, though property rights have proven remarkably durable across successive administrations.
Short-Term Rental Regulation Tightening
Barcelona has already moved aggressively to restrict short-term rental licences, and similar pressures are building in Lisbon and several Algarve municipalities. Buyers whose investment case is materially dependent on short-term rental income should prioritise properties with existing, transferable licences - a finite and increasingly valuable asset class within each market.
Off-Plan Supply in Spain
The new-build pipeline across the Costa del Sol and Costa Blanca has expanded significantly, with several large master-planned communities set to deliver from 2025–2027. This supply expansion is likely to create pockets of softness in the €400,000–€700,000 segment while leaving ultra-prime and resale inventory largely unaffected. Buyers in this price range should negotiate hard on developer incentives and build-quality specifications.
Ready to Explore European Opportunities?
Our advisors specialise in guiding Australian buyers through the European acquisition process - from market selection and currency strategy to legal structuring and property management.
Request a Private Consultation